

Wall Street is facing a problem that isn't coming from the stock market this time.
It's coming from bonds.
U.S. Treasury yields have climbed to levels not seen in more than two decades, forcing investors to rethink the outlook for inflation, interest rates and the government's growing borrowing needs.
The benchmark 10-year Treasury yield rose as high as 5.364% on October 7, its highest level since 2002. The 30-year yield also touched a 24-year high of around 5.70% before both pulled back following a strong government bond auction.
The move matters because Treasury yields influence much more than the bond market.
They feed into mortgage rates, corporate borrowing costs, stock valuations and, ultimately, the financial conditions the Federal Reserve is trying to manage.
For investors who had grown accustomed to record-high equity markets, the latest bond selloff is becoming harder to dismiss.
WHAT HAPPENED?
U.S. government bonds came under renewed selling pressure this week, pushing yields sharply higher.
When bond prices fall, yields rise.
The 10-year yield briefly moved above 5.36%, while the 30-year yield approached 5.70%.
Several forces are behind the move.
Oil prices climbed back above $100 a barrel as geopolitical tensions raised concerns about energy supplies. Higher energy costs have revived worries that inflation could prove more persistent than expected, potentially keeping interest rates higher for longer.
At the same time, investors are paying closer attention to the sheer amount of debt the U.S. government needs to issue.
Together, those concerns have increased the return investors want before committing money to longer-term Treasury securities.
WHY ARE INVESTORS WORRIED?
The headline numbers are striking, but the bigger concern is what is driving them.
Higher yields can be a sign of a healthy economy and stronger growth. That is not necessarily a bad thing for markets.
The problem is that today's rise is also tied to inflation concerns, fiscal pressure and uncertainty over where interest rates are ultimately headed.
That combination makes investors uncomfortable.
If yields are rising because economic growth is accelerating, markets can often absorb the move.
But if yields are rising because inflation remains stubborn while the government continues to borrow heavily, the consequences are less straightforward.
The key question for investors is becoming:
How high can borrowing costs go before they begin to weigh on economic growth?
OIL IS MAKING THE BOND MARKET'S JOB HARDER
Energy prices have become an important part of the story.
Brent crude recently moved above the psychologically important $100-per-barrel mark as the conflict involving Iran and wider regional supply risks continued to influence markets.
Higher oil prices can quickly feed into the broader economy.
Fuel costs rise. Transportation becomes more expensive. Airlines face higher operating expenses, while manufacturers and distributors pay more to move goods.
Eventually, some of those costs can reach consumers.
That creates a fresh problem for the Federal Reserve. If energy prices keep inflation elevated, declaring victory over inflation becomes more difficult.
Investors may then demand higher returns on long-term Treasury bonds to compensate for the risk of persistent inflation.
The chain reaction is straightforward:
Oil rises → inflation concerns increase → rate expectations shift → Treasury yields rise → borrowing costs increase.
THE FED IS NOW WALKING A TIGHTROPE
The Federal Reserve raised interest rates at its September meeting, marking its first rate increase since July 2023.
But the latest meeting minutes showed that policymakers remain divided over how future decisions should respond to inflation and economic conditions.
Some officials saw higher rates as necessary to contain the inflationary effects of energy shocks. Others placed greater emphasis on demand-driven inflation.
Then came a weak September jobs report.
The U.S. economy added just 29,000 jobs in September, while unemployment rose to 4.2%.
Under normal circumstances, weaker employment would strengthen the case for lower interest rates.
But higher energy prices are pulling policy in the opposite direction.
The Fed is therefore dealing with an uncomfortable combination:
A cooling labour market alongside renewed inflation risks.
That leaves policymakers with considerably less room to maneuver.
THE MARKET IS NOT EXPECTING AN IMMEDIATE FED HIKE
Despite the sharp increase in long-term Treasury yields, markets have actually become less convinced that the Fed will raise rates again at its October meeting.
According to CME FedWatch data reported by Reuters, traders were assigning less than a 20% probability to another October hike, down from 37.6% a week earlier.
At first glance, that may seem contradictory.
If investors expect fewer rate increases, why are long-term yields going up?
The answer is that the bond market is looking beyond the next Fed meeting.
Investors are increasingly focused on longer-term inflation, government borrowing requirements and the amount of compensation they need to hold long-dated Treasury debt.
The message isn't necessarily:
"The Fed is about to raise rates."
It may be closer to:
"Borrowing costs could remain high for much longer than previously expected."
AMERICA'S DEBT LOAD IS BECOMING PART OF THE STORY
The U.S. government needs to issue enormous amounts of debt to finance spending and existing obligations.
That means investors must continually absorb large Treasury offerings.
As the supply of government bonds increases, demand becomes even more important.
If investors become less willing to hold long-duration Treasuries, yields may need to rise to attract enough buyers.
That is why every major Treasury auction is being watched closely.
This week's $39 billion 10-year Treasury auction offered some reassurance.
Demand was stronger than some investors had feared. The auction produced a bid-to-cover ratio of 2.77, above the recent six-auction average of 2.54. Primary dealers took just 2.5% of the offering, their smallest share since the aftermath of the global financial crisis.
The strong demand helped calm the market and pushed yields away from their session highs.
But it did not remove the broader concerns surrounding U.S. borrowing.
WHY STOCKS ARE GETTING NERVOUS
Higher Treasury yields can create pressure on equities in two ways.
First, government bonds become more attractive relative to stocks when their yields rise.
Second, higher interest rates increase the discount rate investors use when valuing future corporate earnings.
That matters particularly for high-growth companies whose valuations depend heavily on profits expected years from now.
Technology stocks are especially sensitive to this dynamic.
The Nasdaq had recently reached record territory, helped by continued enthusiasm surrounding artificial intelligence. But rising bond yields make investors less willing to pay extremely high prices for future earnings.
On Wednesday, the Nasdaq fell 0.24%, while the S&P 500 declined 0.23% and the Dow dropped 0.69%.
It wasn't a market rout.
But it was another reminder that rising yields are becoming an increasingly important risk for equities.
HOUSING FEELS THE PRESSURE FIRST
One of the most visible effects of higher Treasury yields is their impact on mortgage rates.
The 30-year fixed mortgage rate recently climbed to a near three-year high, according to the Mortgage Bankers Association.
That puts additional pressure on homebuyers and can weigh on housing demand, refinancing activity and homebuilders.
Commercial real estate also faces a tougher financing environment.
Businesses can feel the impact as well, particularly when higher borrowing costs make companies more cautious about taking on new debt or investing in expansion.
For consumers, the effects can extend beyond mortgages to credit cards, auto loans and other forms of financing.
The bond market may seem far removed from everyday spending.
In reality, its moves can eventually show up in household budgets.
THE "BEAR STEEPENER" SIGNAL
Another development attracting attention is the changing shape of the Treasury yield curve.
The gap between the two-year and 10-year Treasury yields widened to around 52 basis points, with long-term yields rising faster than short-term yields.
That is known as a bear steepener.
The move can indicate that investors are becoming more concerned about longer-term inflation, government borrowing or broader economic risks rather than simply anticipating an immediate change in Federal Reserve policy.
In simpler terms, the market may be saying:
The short-term outlook is uncertain, but the longer-term risks are becoming harder to ignore.
WALL STREET'S BIG PARADOX
There is a striking contradiction in U.S. markets right now.
Stocks have recently been trading near record highs while Treasury yields have climbed toward levels last seen more than two decades ago.
Those two trends don't naturally fit together.
High stock valuations require confidence in future earnings.
Higher Treasury yields make those future earnings worth less in today's terms.
That puts greater pressure on companies to deliver strong results if equity valuations are going to remain elevated.
The third-quarter earnings season will therefore be closely watched.
Analysts are expecting roughly 30.6% year-on-year growth in S&P 500 earnings for the July–September period, according to LSEG data cited by Reuters.
If companies deliver those profits, stocks may prove more resilient even with higher bond yields.
If earnings disappoint, the bond market could become a much bigger problem for equities.
THE GLOBAL EFFECT
The U.S. Treasury market sits at the heart of global finance.
When American yields rise sharply, the effects can quickly spread beyond the United States.
Global investors compare returns across government bond markets. Higher U.S. yields can attract capital toward dollar-denominated assets, potentially strengthening the dollar and putting pressure on emerging-market currencies.
Countries carrying large amounts of dollar-denominated debt can also face higher financing costs.
Global stock markets may feel the pressure as well.
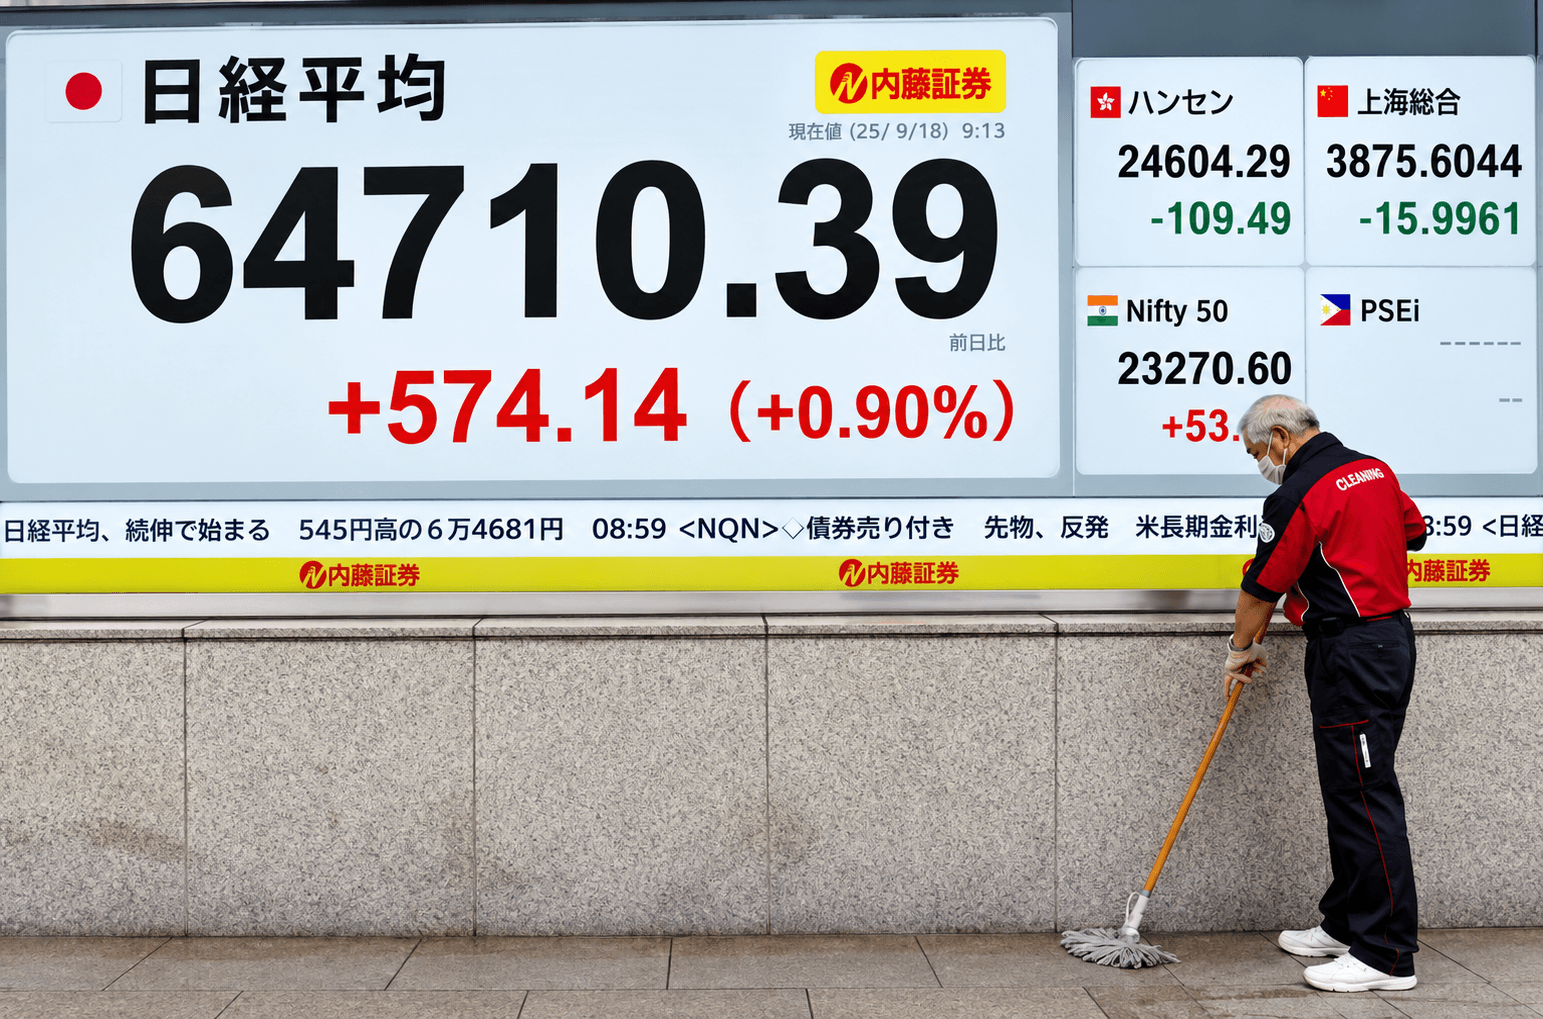
Asian markets were already lower on Thursday as investors responded to higher U.S. yields and rising oil prices.
For India and other emerging economies, the combination of expensive oil, a stronger dollar and higher U.S. yields is particularly important.
FACT CHECK METER
FACT METER: 98%
STATUS: DEVELOPING
CONFIRMED
The U.S. 10-year Treasury yield reached approximately 5.364%, a 24-year high, on October 7.
The 30-year Treasury yield reached approximately 5.70%, also a multi-decade high.
A $39 billion 10-year Treasury auction attracted strong demand and helped yields retreat from their highs.
Wall Street's major indexes closed lower as Treasury yields climbed.
Higher oil prices have increased concerns about renewed inflation pressure.
Federal Reserve minutes from the September meeting showed disagreement among policymakers over inflation risks and the future path of rates.
IMPORTANT DISTINCTION
Higher Treasury yields do not automatically mean a financial crisis is coming.
The strong demand at the latest 10-year auction shows that investors remain willing to buy U.S. government debt, even at elevated yields.
The bigger question is whether high yields remain elevated for long enough to hurt housing, corporate investment, consumer spending and equity valuations.
AWX VERDICT
The bond market is sending a warning — not declaring an emergency.
The immediate concern is not a collapse in demand for Treasuries.
It is the possibility that inflation, energy prices and government borrowing keep long-term yields elevated for an extended period.
AWX FOCUS
Wall Street is watching three numbers particularly closely.
5.36%
The recent peak for the 10-year Treasury yield.
A sustained move above that level would mark another significant tightening in financial conditions.
5.70%
The recent peak for the 30-year Treasury yield.
That level matters because long-term Treasury yields have a direct influence on mortgages and other forms of long-term borrowing.
$100
The oil-price threshold that has become psychologically important for inflation expectations.
If oil stays above $100 for an extended period, the Federal Reserve's job becomes considerably harder.
WHAT TO WATCH NEXT
1. THE 10-YEAR TREASURY
Will yields remain above 5%, or will they retreat toward lower levels?
2. OIL PRICES
Another sustained rally in crude could push inflation expectations higher.
3. FED COMMUNICATION
Investors will be looking for clues about whether policymakers can remain on hold while inflation risks persist.
4. TREASURY AUCTIONS
Strong demand would provide reassurance. Weak auctions could increase concerns about the government's borrowing requirements.
5. CORPORATE EARNINGS
Companies will need to show that earnings growth can support current equity valuations despite higher financing costs.
6. THE DOLLAR
A prolonged rise in U.S. yields could strengthen the dollar and add pressure to emerging markets.
THE AWX BOTTOM LINE
The stock market usually gets the headlines.
Right now, however, the bond market is sending the more important signal.
A 10-year Treasury yield above 5.3% changes the financial equation for Wall Street.
It raises mortgage costs.
It increases government financing expenses.
It makes corporate borrowing more expensive.
And it puts additional pressure on already-expensive stock valuations.
The strong Treasury auction offered some relief, but it hasn't answered the bigger question.
Can the United States continue borrowing at this scale without forcing investors to demand substantially higher yields?
For now, there is no clear answer.
And that uncertainty is exactly what is keeping Wall Street on edge.
ATTLAS WIRE | AWX WORLD NEWS
Real Stories. Lasting Impact.
Comments
No comments yet.