

The global economy is facing another energy test.
Brent crude moved back above $100 a barrel on Thursday, rising past $102 as fresh attacks on shipping around the Gulf and growing risks around the Strait of Hormuz raised concerns about the safety and cost of global oil supplies.
U.S. West Texas Intermediate also moved higher, trading around $90 a barrel.
The rise comes even as governments and international agencies work to release emergency oil stocks. For investors and businesses, however, the concern is no longer just how much oil is available. It is also becoming a question of how much it costs to move that oil safely around the world.
That distinction matters.
Shipping insurance premiums are rising. Tanker rates have jumped. Some vessels are taking longer routes to avoid dangerous waters, while severe weather is disrupting U.S. offshore production.
Together, those pressures are increasing the real cost of energy.
And that cost rarely stays within the energy market for long. It can spread into freight, manufacturing, agriculture, aviation, retail and eventually consumer prices.
WHAT HAPPENED?
Oil prices jumped again as traders reacted to renewed attacks on tankers in the Gulf and growing security concerns around the Strait of Hormuz.
Brent crude climbed to around $102.28 a barrel, while WTI moved toward $90.
The latest increase followed an attack on a tanker north of Qatar that reportedly caused casualties.
Maritime security concerns have intensified as the conflict involving the United States, Israel and Iran continues.
The Strait of Hormuz remains especially important to global energy markets. Before the current disruption, the waterway handled shipments equivalent to roughly 20% of global oil and fuel flows.
Even if oil continues to move through the strait, higher insurance premiums, security costs and shipping rates can make each barrel more expensive to deliver.
That is where businesses are beginning to feel the pressure.
THE REAL COST OF OIL IS RISING
The benchmark price of crude only tells part of the story.
For companies, the price that matters is the cost of getting energy to where it is actually needed.
Oil has to be transported, insured, refined and distributed before it becomes gasoline, diesel, jet fuel or an industrial input.
Those costs have been rising sharply.
The U.S. Energy Information Administration has pointed to higher shipping costs and increased risk premiums as tanker operators face greater risks in the region.
Tanker rates reached record levels in September, while higher insurance costs and longer routes have reduced the effective availability of vessels.
That means companies can face significantly higher energy expenses even if the headline crude price does not rise by the same amount.
SHIPPING IS BECOMING THE HIDDEN INFLATION TAX
Transportation is one of the biggest pressure points for the global economy.
Companies do not simply buy oil. They also have to move goods.
That means relying on ships, trucks, aircraft and warehouses.
When fuel costs rise, each stage of that chain becomes more expensive.
The Middle East disruption is adding another layer of pressure. Higher security risks are forcing some vessels to change routes, while longer journeys increase fuel consumption and reduce vessel availability.
Shipping costs have risen sharply since the conflict involving Iran began, according to industry reporting. Ship-to-ship transfers around Hormuz have also added another layer of expense.
The result is a physical supply chain that is becoming more expensive even when the crude benchmark does not fully reflect those additional costs.
TRUCKING AND DIESEL ARE UNDER PRESSURE
For many businesses, diesel matters more than the price of crude itself.
Trucks move food, construction materials, manufactured products and consumer goods across economies.
When diesel becomes more expensive, transportation companies immediately face higher operating costs.
Farmers are exposed as well. Tractors, harvesting equipment and farm transportation all depend heavily on diesel.
The U.S. services sector is already showing signs of the pressure.
The latest Institute for Supply Management survey found businesses increasingly reporting higher fuel costs. The prices-paid measure for services companies rose to 74.0, its highest level since July 2022.
That is an important warning sign.
Higher energy costs are beginning to work their way through business supply chains.
MANUFACTURERS ARE GETTING SQUEEZED
Manufacturers are facing pressure from both sides.
Factories consume energy directly, but they also depend on energy-intensive supply chains.
Steel, chemicals, plastics, fertilizers and other industrial materials can all become more expensive when energy prices rise.
Companies then have a difficult choice:
Absorb the additional cost.
Raise prices.
Cut production.
Delay investment.
Large corporations may have enough financial flexibility to absorb a temporary shock.
Smaller businesses often have much less room to maneuver.
S&P Global has warned that oil prices above $100 are putting additional pressure on freight, manufacturing and household costs across Asia, where many economies rely heavily on imported energy.
AIRLINES FACE ANOTHER FUEL TEST
Airlines are among the businesses most exposed to higher energy prices.
Jet fuel is one of their biggest operating expenses.
When crude prices rise, fuel bills can increase quickly, putting pressure on ticket prices, profit margins and route profitability.
Airlines can protect themselves to some extent through fuel hedging, which can delay the impact of higher prices.
But those protections do not last forever.
If crude remains elevated for an extended period, higher fuel costs eventually feed through to airline operations.
The impact can also reach air cargo, making it more expensive for companies that depend on fast international shipping.
FOOD COSTS COULD FOLLOW
Energy and food markets are closely connected.
Farmers need diesel for tractors and harvesting equipment. Food processors need electricity and fuel. Trucks transport crops and finished products, while ships move commodities across international markets.
Fertilizer production is also closely tied to energy prices.
As a result, a sustained oil shock can eventually show up in food prices even when agricultural production itself remains relatively strong.
The risk becomes more significant when food markets are already dealing with weather-related disruptions.
Higher fuel costs could add another source of pressure to global food inflation.
U.S. INVENTORIES ARE FALLING
The latest U.S. inventory figures are adding to market concerns.
U.S. crude inventories fell by 3.2 million barrels in the week ended October 2, leaving stocks at around 424.1 million barrels.
The decline was larger than analysts had expected.
Distillate inventories, which include diesel and heating oil, also fell slightly and remain below typical levels for this time of year.
That matters because diesel is already one of the tighter parts of the fuel market.
When inventories are low, another supply disruption can have a much larger effect on prices.
AMERICA'S GULF OF MEXICO IS ALSO UNDER PRESSURE
The Middle East is not the only source of supply disruption.
A major storm approaching the U.S. Gulf of Mexico has forced energy companies to shut down some offshore production.
Shell and Chevron have curtailed operations as the storm moves closer.
Government data showed that roughly 25% of Gulf of Mexico oil production and more than 16% of natural-gas production had been shut in as of Wednesday.
That creates a difficult combination for the market:
Geopolitical disruption overseas.
Weather-related disruption at home.
Temporary production losses can have an outsized effect when global inventories are already under pressure.
EMERGENCY OIL RELEASES CAN BUY TIME — NOT CREATE OIL
Governments are trying to prevent the current shock from becoming worse.
The International Energy Agency has agreed to accelerate the release of oil stocks and prioritize diesel supplies as part of measures introduced during the crisis.
Those steps can provide additional supply in the short term.
But there is an obvious limitation.
Strategic reserves are a buffer. They are not new production.
Once emergency stocks are released, those barrels are no longer available for the next major disruption.
Reserve releases can therefore soften a supply shock, but they cannot permanently solve a structural shortage or geopolitical problem.
BUSINESSES ARE FACING A THREE-WAY SQUEEZE
The current environment is particularly difficult because companies are dealing with several pressures at the same time.
ENERGY COSTS
Oil and diesel prices are rising.
SHIPPING COSTS
Insurance, freight rates and vessel availability are under pressure.
FINANCING COSTS
Higher inflation expectations are pushing bond yields higher and keeping borrowing conditions tight.
That combination can quickly squeeze corporate margins.
A company may be able to absorb one higher input cost.
It becomes much harder when energy, transportation and financing costs all rise together.
HIGHER COSTS COULD REACH CONSUMERS
Businesses can absorb higher costs for only so long.
If the pressure continues, companies usually have to make adjustments.
Some will raise prices.
Others will accept lower margins.
Some may reduce investment, hiring or production.
That is why oil above $100 is about more than the energy market.
It is also an inflation story.
Recent U.S. services-sector data shows businesses reporting higher fuel, steel and other input costs, with some companies warning that expensive transportation is adding to operating expenses.
If those costs are passed on to customers, consumers could eventually feel the impact.
ASIA MAY FACE THE BIGGEST PRESSURE
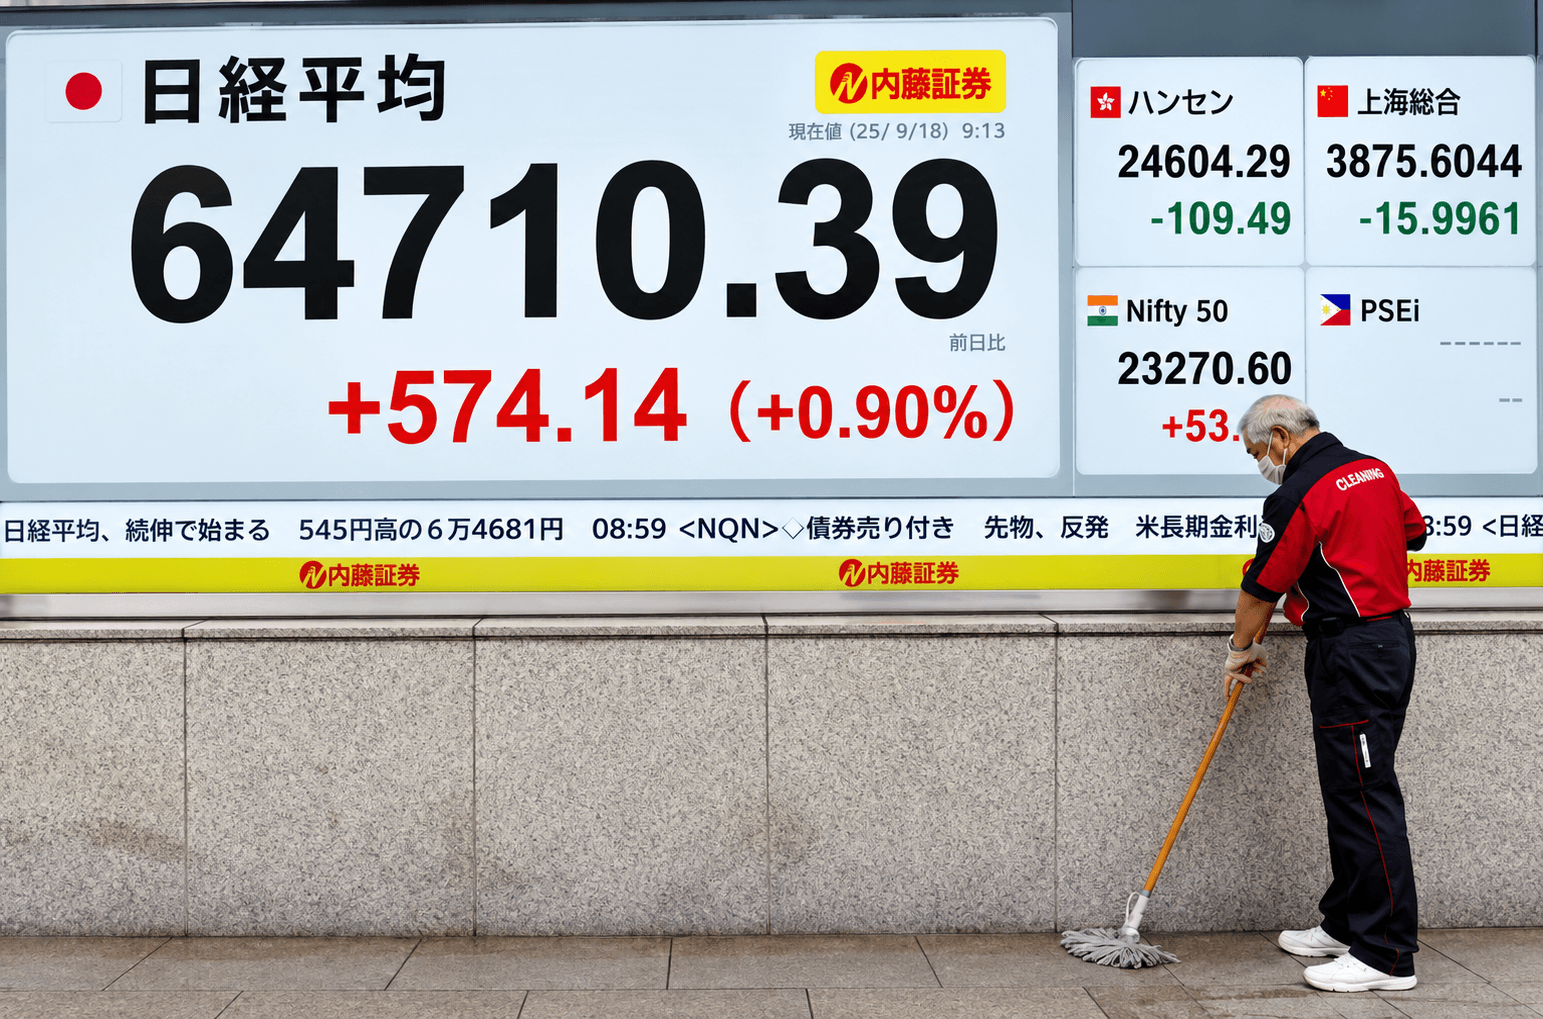
Asia is particularly vulnerable to higher oil prices because many economies in the region depend heavily on imported energy.
S&P Global estimates that around 75% of Asia's Middle Eastern crude imports moved through the Strait of Hormuz in 2025.
Although trade patterns have changed significantly during the current crisis, the region remains exposed to disruptions around the waterway.
Higher oil prices can weaken trade balances, put pressure on currencies and reduce household spending.
Businesses may also reduce production when energy costs become too high.
That creates the possibility of demand curtailment — companies and consumers simply using less because energy has become too expensive.
INDIA'S EXPOSURE
India is also watching the oil market closely.
The country imports a large share of the crude it consumes, making international oil prices important for inflation, the currency and the current account.
Higher crude prices can raise transportation and manufacturing costs while putting additional pressure on household budgets.
India's inflation outlook is already being shaped by food and energy prices.
A Reuters poll found economists expected Indian consumer inflation to rise to around 5.4% in September, compared with 4.82% in August, with food and energy costs among the factors behind the increase.
The Reserve Bank of India has also raised its policy rate, highlighting concerns about renewed inflationary pressure.
THE FED HAS ANOTHER PROBLEM
The U.S. Federal Reserve faces a similar challenge.
Higher oil prices can push inflation upward at a time when policymakers are still assessing the direction of monetary policy.
Recent U.S. services data showed input-price pressures reaching their highest level since 2022.
If companies begin passing those higher costs more aggressively to customers, inflation could prove more persistent.
That could keep interest rates higher for longer.
For businesses already dealing with expensive energy and shipping, higher borrowing costs would add another layer of pressure.
THE BIGGER GLOBAL RISK
The biggest concern is not simply whether oil reaches $105 or $110.
It is whether markets begin to believe that high energy prices are here to stay.
A short-lived spike can often be absorbed.
A prolonged energy shock is much harder to manage.
If companies expect fuel costs to remain high for months, they may begin changing contracts, pricing strategies, investment plans and hiring decisions.
That is when an energy crisis starts influencing broader economic behavior.
WHY THIS MATTERS
Oil remains one of the world's most important economic inputs.
It affects transportation.
It affects manufacturing.
It affects agriculture.
It affects aviation.
It affects logistics.
And it affects inflation.
That makes the latest move above $100 more than another commodity-market headline.
It is a warning about the rising cost of doing business around the world.
The longer oil stays elevated, the more difficult it becomes for companies to decide whether to absorb the additional cost or pass it on to customers.
FACT CHECK METER
FACT METER: 98%
STATUS: DEVELOPING
CONFIRMED:
Brent crude moved back above $100 on October 8, with prices rising above $102 as shipping attacks and concerns over Middle East supply intensified.
CONFIRMED:
The Strait of Hormuz previously handled shipments equivalent to roughly one-fifth of global oil and fuel flows.
CONFIRMED:
U.S. crude inventories fell by 3.2 million barrels in the latest weekly data, while distillate inventories remained below seasonal averages.
CONFIRMED:
U.S. services businesses are reporting significant fuel and input-cost pressure, with the ISM prices-paid index reaching its highest level since July 2022.
IMPORTANT DISTINCTION:
Oil above $100 does not automatically mean a global recession is coming. Much will depend on how long prices remain elevated and whether supply disruptions become more severe.
AWX VERDICT:
The immediate risk is a prolonged cost shock rather than an outright global oil shortage. Businesses are dealing with higher fuel, freight and insurance costs at a time when financing conditions remain tight.
AWX FOCUS
The most important number may not be $100.
It may be the cost of getting a barrel of oil from the producer to the customer.
Oil can continue flowing through Hormuz while businesses still pay considerably more because of insurance premiums, security concerns, tanker shortages and longer routes.
That means the global economy can face an energy squeeze without experiencing a complete physical shutdown of oil supplies.
For companies, that may be the most difficult part of the current crisis.
WHAT TO WATCH NEXT
1. BRENT CRUDE
Whether oil remains above $100 or moves toward new highs.
2. HORMUZ SHIPPING
Any further attacks on tankers could quickly push freight and insurance costs higher.
3. DIESEL PRICES
Tight diesel markets could transmit higher costs into trucking, farming and manufacturing.
4. U.S. INVENTORIES
Further declines could intensify concerns about available supply.
5. GLOBAL FREIGHT RATES
Higher shipping costs could become another channel for inflation.
6. CENTRAL BANKS
Watch whether rising energy costs change expectations for interest-rate policy.
7. CORPORATE EARNINGS
Companies will increasingly reveal how much of the energy shock they can absorb and how much they intend to pass on.
THE AWX BOTTOM LINE
Oil above $100 is becoming more than a market headline.
It is becoming a business-cost problem.
Companies are facing higher fuel bills, expensive shipping, tighter diesel supplies and rising insurance costs — all while borrowing remains relatively expensive.
Emergency oil releases can provide temporary relief.
They cannot, however, remove the geopolitical risks surrounding some of the world's most important energy routes.
If oil falls quickly, many businesses may be able to absorb the shock.
If it stays above $100 for months, the consequences could become much broader.
The next phase of the oil crisis may be measured not by barrels lost, but by costs passed from energy markets to businesses — and from businesses to consumers.
ATTLAS WIRE | AWX WORLD NEWS
Real Stories. Lasting Impact.
Comments
No comments yet.