
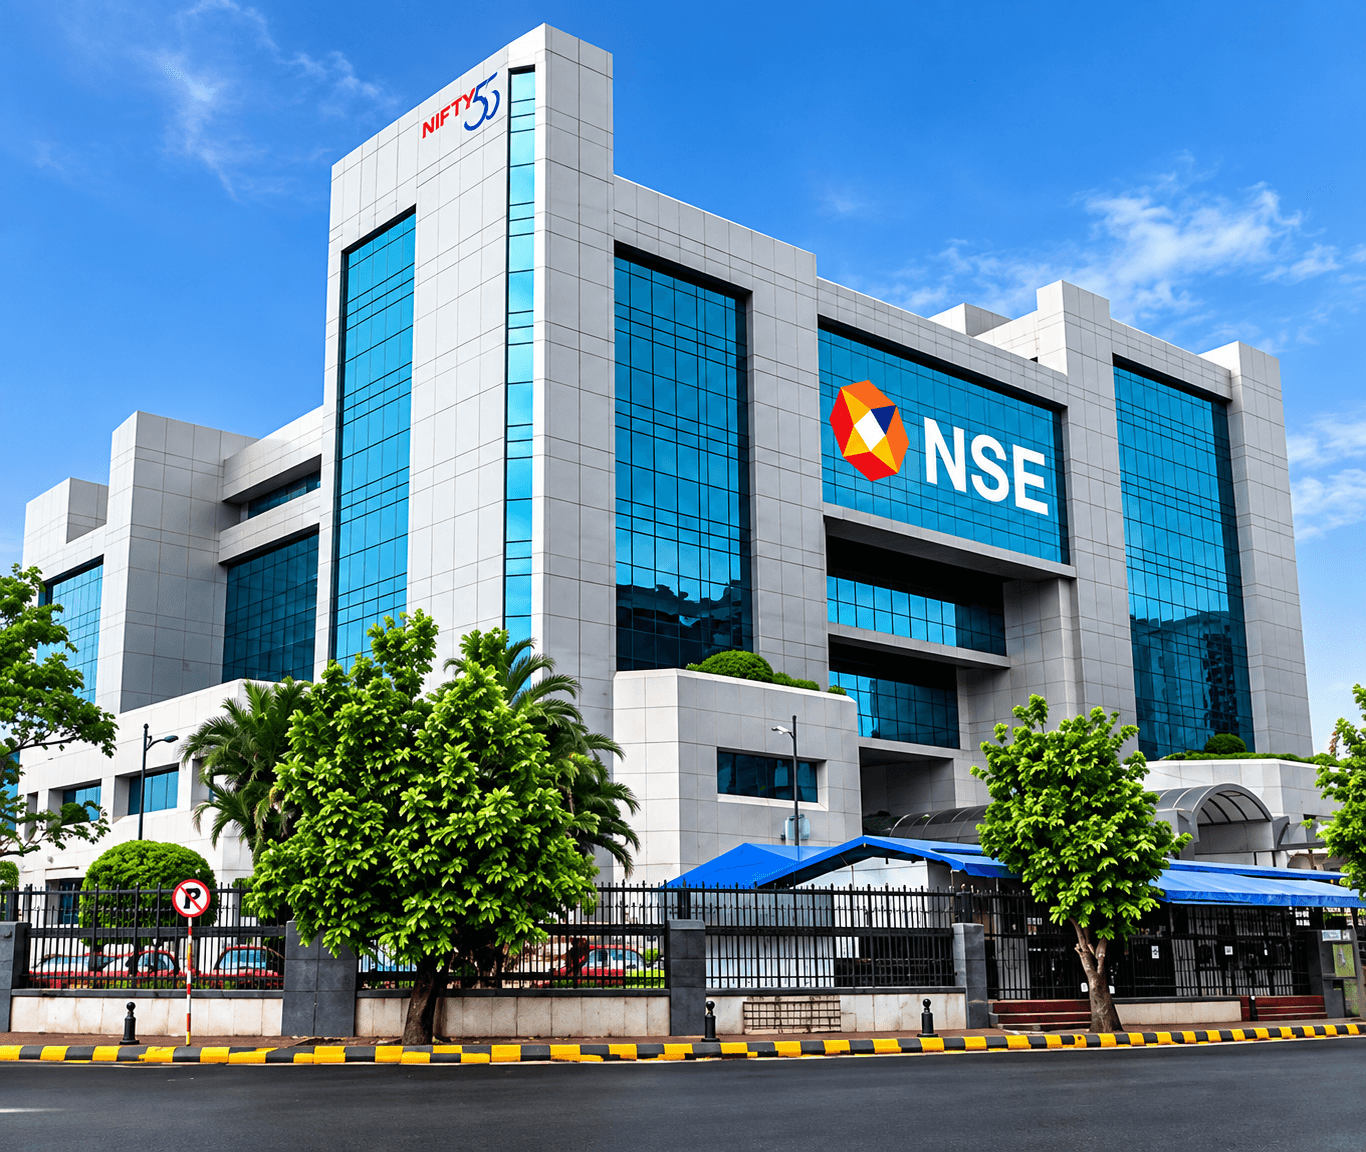
The National Stock Exchange of India has completed its long-awaited transition into a publicly traded company.
But its IPO has also brought a familiar question back into focus:
Why can't India's biggest stock exchange trade its own shares on its own platform?
For now, it cannot. Under the existing framework, NSE shares are listed on BSE rather than NSE.
The reason is largely about avoiding conflicts of interest.
A stock exchange is not just a trading venue. It is also a regulated market infrastructure institution responsible for surveillance, disclosures, trading rules and investor protection. Allowing it to oversee trading in its own shares could raise questions about whether that oversight is truly independent.
For now, BSE provides the independent market on which NSE shares trade.
But discussion about whether NSE could eventually seek permission to trade its own stock has brought the issue back into India's wider capital-market debate.
WHAT HAPPENED?
NSE's IPO marked the end of a decade-long effort to bring the exchange into the public markets.
The offering raised about $2.3 billion and attracted strong investor demand.
NSE began trading publicly on September 24, with its shares listed on BSE rather than NSE.
That arrangement follows the existing regulatory structure.
The bigger issue, however, goes beyond where investors buy and sell NSE shares.
It raises a fundamental question about market governance:
Should a market operator ever be allowed to run the trading venue for its own securities?
WHY CAN'T NSE LIST ON NSE?
The main concern is the potential conflict of interest.
Stock exchanges are expected to provide fair, transparent and orderly markets. They also monitor listed companies and trading activity taking place on their platforms.
If an exchange were itself one of the securities being traded, questions could arise over how it handles matters such as:
Trading surveillance
Market disclosures
Corporate announcements
Price-sensitive information
Trading halts
Regulatory compliance
Investor protection
The concern is not necessarily that an exchange would misuse its position.
Rather, regulators generally want the structure itself to minimise the possibility — or even the appearance — of self-supervision.
That is why NSE's shares are currently traded on BSE.
THE CROSS-LISTING PARADOX
India's two major stock exchanges now occupy an unusual position.
BSE is a publicly traded company whose shares trade on NSE.
NSE is a publicly traded company whose shares trade on BSE.
It is an unusual arrangement, but it also creates a degree of separation.
Each exchange provides the trading infrastructure for the other exchange's shares, allowing investors to buy and sell the stock without the exchange directly operating the market for its own securities.
That arrangement also adds an element of external oversight to the trading process.
WHY NSE MAY WANT ITS OWN TRADING VENUE
There are obvious commercial reasons why NSE could eventually be interested in having its shares traded on its own platform.
NSE is India's dominant exchange by trading activity across major segments and has a huge investor base.
Listing its shares directly on its own platform could increase visibility and potentially make the stock even more accessible to retail investors.
It could also create a more direct connection between NSE and the investors who use its marketplace every day.
But convenience alone would not settle the issue.
The regulatory and governance questions would remain the most important part of any such proposal.
THE SEBI QUESTION
The Securities and Exchange Board of India, or SEBI, would be central to any discussion about changing the current framework.
SEBI regulates India's securities markets and oversees market infrastructure institutions, including stock exchanges.
Recent comments from SEBI leadership indicated that the regulator had not received a formal proposal from NSE seeking approval to trade its own shares on NSE.
That distinction is important.
There is a significant difference between an idea being discussed and a formal regulatory proposal being submitted.
For now, there is no approved arrangement allowing NSE shares to trade on NSE.
THE GOVERNANCE PROBLEM
Opponents of self-trading argue that the arrangement could create difficult governance questions.
Consider what could happen if NSE itself were the company whose shares were experiencing unusual trading activity.
Who would monitor that trading?
Who would decide whether trading should be halted?
Who would handle market-sensitive announcements?
Who would investigate potential violations?
And who would take action if NSE's own shares experienced extreme volatility?
Even with sophisticated technology and strict internal controls, those questions would remain.
That is the core reason independent oversight matters.
THE CASE FOR REFORM
Supporters of reform could argue that financial-market technology and regulatory systems have evolved considerably.
Modern exchanges operate sophisticated surveillance systems, maintain independent governance structures and are subject to extensive regulatory oversight.
In theory, a future framework could separate the operation of NSE's trading platform from the supervision of trading in NSE's own shares.
An independent regulator or another external mechanism could potentially oversee specific aspects of the stock's trading activity.
But such a system would require strong safeguards.
So the debate is not simply about whether NSE should self-list.
The bigger question is:
Can self-trading be designed in a way that does not compromise market integrity?
THE INVESTOR ANGLE
For investors, the issue has a more practical side.
NSE is now a publicly traded company whose financial performance is closely linked to activity across India's capital markets.
Its business spans areas including:
Equity trading
Equity derivatives
Market data
Clearing and settlement
Listing services
Technology infrastructure
Because of NSE's importance to India's financial system, its shares are likely to receive significant attention from institutional and retail investors.
Where those shares trade could therefore become an important part of the wider discussion about India's market structure.
BSE'S POSITION
The debate also has direct implications for BSE.
BSE currently provides the trading venue for NSE shares. If NSE were eventually permitted to trade its own stock, some of that activity could potentially shift away from BSE.
That could affect trading volumes and the competitive balance between India's two major exchanges.
BSE has already benefited from becoming the venue for NSE's public listing.
A future regulatory change could alter that dynamic.
The self-listing debate is therefore not just about NSE. It is also indirectly about the competitive relationship between NSE and BSE.
WHY THIS MATTERS
1. IT TESTS INDIA'S MARKET GOVERNANCE
The debate goes directly to the principles of independent supervision, transparency and market integrity.
2. NSE IS NOW A PUBLIC COMPANY
The issue has greater significance now that NSE shares are available to public-market investors.
3. BSE PROVIDES AN INDEPENDENT VENUE
NSE's listing on BSE gives investors a separate exchange through which they can trade the stock.
4. SELF-TRADING COULD CHANGE THE COMPETITIVE BALANCE
If NSE were eventually allowed to trade its own shares, BSE could potentially lose some of the trading activity currently associated with NSE stock.
5. SEBI HOLDS THE KEY
Any change to the existing framework would ultimately require regulatory consideration and appropriate safeguards.
FACT CHECK METER
AWX FACT CHECK
STATUS: DEVELOPING
CONFIRMED
NSE has become a publicly traded company following its IPO.
NSE shares are listed on BSE rather than NSE.
The existing framework does not allow an exchange to simply list and trade its own securities on its own platform.
Potential conflicts of interest are a central concern in allowing an exchange to oversee trading in its own shares.
SEBI has indicated that it had not received a formal proposal from NSE seeking approval to trade its own shares on NSE.
NOT INDEPENDENTLY VERIFIED
Whether NSE will formally seek permission to trade its shares on its own platform.
Whether SEBI would approve such a proposal.
What specific safeguards could be introduced if the current framework were reconsidered.
CURRENT MODEL
NSE shares trade on BSE, giving investors an independent exchange venue for the stock.
SELF-LISTING CASE
Supporters could argue that stronger technology, surveillance systems and independent regulatory supervision could potentially make self-trading possible.
REGULATORY CASE
Opponents argue that allowing an exchange to trade its own shares could create conflicts of interest and weaken the principle of independent market oversight.
AWX VERDICT
NSE PUBLIC LISTING: CONFIRMED
NSE SELF-TRADING: NOT APPROVED
REGULATORY DEBATE: DEVELOPING
FUTURE SELF-LISTING: UNCERTAIN
WHAT TO WATCH NEXT
SEBI
Whether the regulator receives a formal proposal concerning the trading of NSE's own shares.
NSE
Whether the exchange seeks changes to the current regulatory framework.
BSE
Whether any future rule change affects trading volumes and investor activity on BSE.
INVESTORS
Whether NSE's public listing changes how investors value India's largest exchange.
REGULATION
Whether SEBI considers new safeguards for the trading of exchange-owned securities.
MARKET STRUCTURE
Whether India moves toward greater competition between NSE and BSE or maintains the current cross-listing arrangement.
THE AWX BOTTOM LINE
The question of whether NSE should trade its own shares is about much more than a listing technicality.
It comes down to one fundamental issue:
Who watches the market watcher?
NSE is now a publicly traded company, but its shares trade on BSE because India's current framework prioritises independent oversight.
The arrangement creates a clear separation:
NSE operates one of India's major markets.
BSE provides the market for NSE's own shares.
Changing that structure would require more than a commercial decision. Regulators would need to be satisfied that surveillance, investor protection and market integrity could remain genuinely independent.
For now, the position is straightforward:
NSE is public, but it is not self-traded.
Whether that changes in the future will depend not only on market demand, but on whether India can design a framework that addresses the conflicts inherent in an exchange trading its own stock.
ATTLAS WIRE | AWX WORLD NEWS
Real Stories. Lasting Impact.



Comments
No comments yet.