

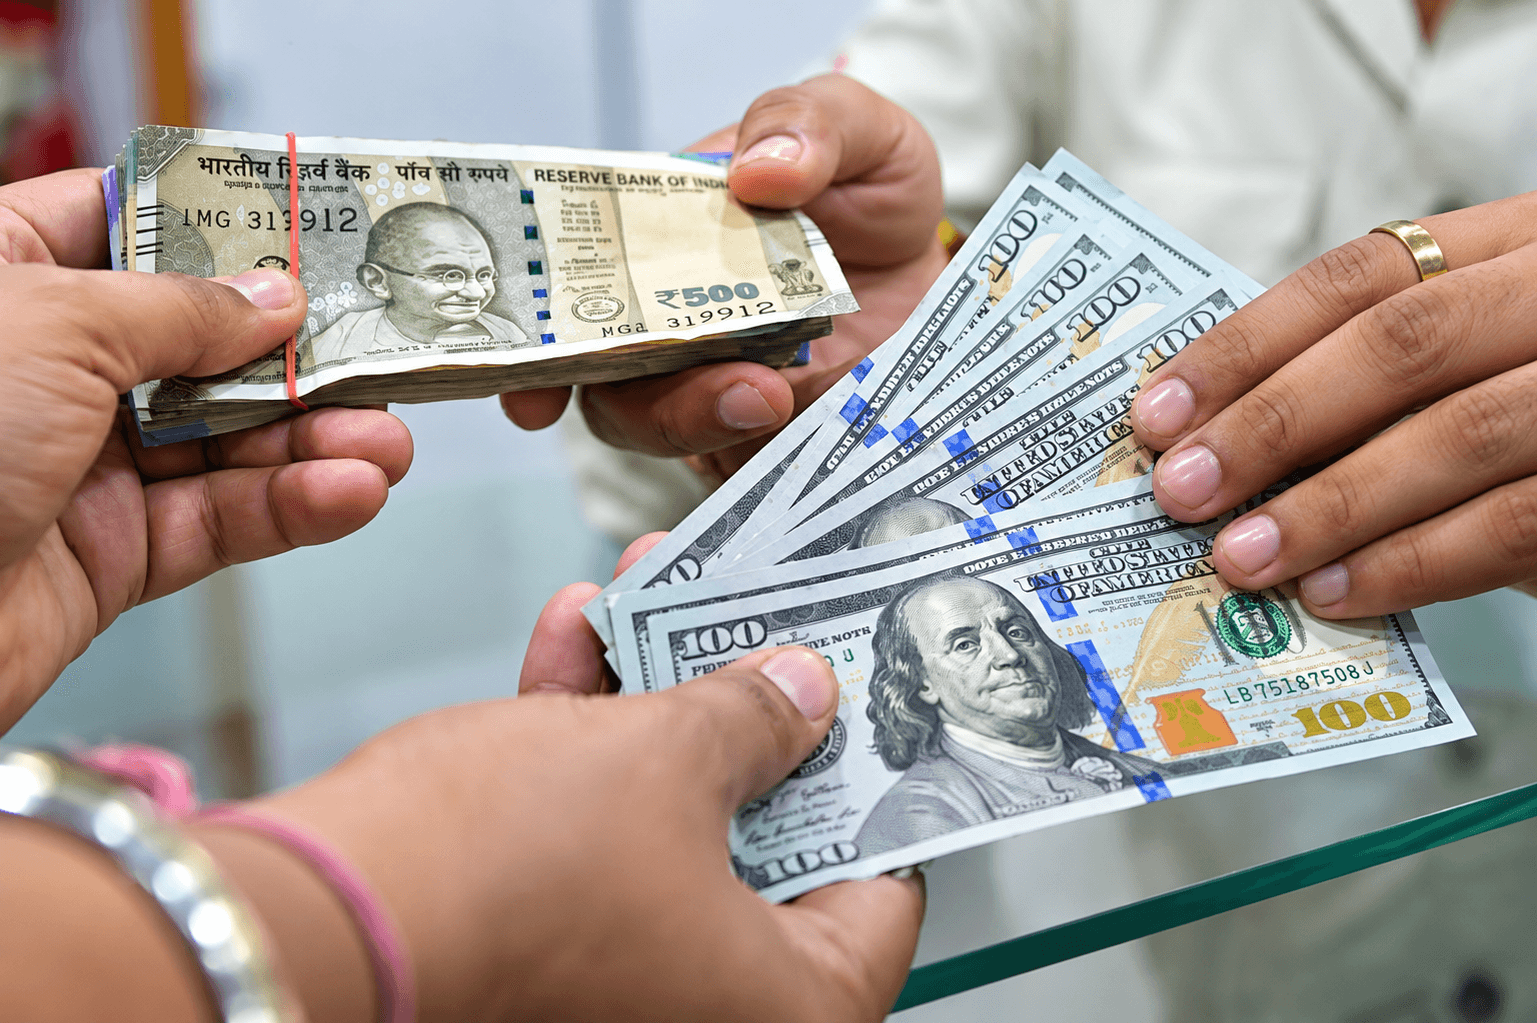
Global currency markets are increasingly favoring the U.S. dollar as investors navigate higher bond yields, rising oil prices and growing concerns about financial stability in Europe.
The euro slipped to around $1.1191 on Thursday, putting it near its lowest level in 17 months. At the same time, the U.S. Dollar Index climbed to roughly 102.32, close to an 18-month high.
Two forces are driving the move.
In the United States, Treasury yields have climbed sharply, with the 10-year yield recently reaching levels not seen since 2002. Minutes from the Federal Reserve also showed that policymakers remain concerned about inflation, leaving the door open to another rate increase later this year.
In Europe, investors are increasingly focused on France's fiscal position, political uncertainty and rising government borrowing costs.
The result is a powerful combination:
Higher U.S. yields are supporting the dollar.
Growing European fiscal concerns are weighing on the euro.
WHAT HAPPENED?
The euro fell toward $1.1191, close to its lowest level in 17 months.
Meanwhile, the dollar index rose to about 102.32, keeping the U.S. currency near its strongest level since April 2025.
The move extends a broader shift in global currency markets, with investors favoring currencies backed by relatively attractive yields and perceived financial stability.
The dollar currently has both advantages.
U.S. Treasury yields remain high, the Federal Reserve is still focused on inflation, and geopolitical uncertainty is encouraging demand for traditional safe-haven assets.
The euro is facing a different set of pressures. Investors are becoming increasingly uneasy about government finances across parts of Europe, particularly France.
WHY IS THE DOLLAR SO STRONG?
The dollar's rise is not simply a reflection of a stronger U.S. economy.
It is increasingly about relative risk and returns.
Investors compare the United States with other major economies when deciding where to hold capital. For now, U.S. Treasury yields remain a major attraction.
The 10-year Treasury yield recently reached around 5.36%, its highest level since 2002.
For global investors, that makes dollar-denominated assets more appealing, particularly when yields elsewhere come with greater fiscal or political risks.
The dollar is also benefiting from uncertainty outside the United States.
Europe is dealing with fiscal concerns. Japan is facing pressure on its bond market and currency. Meanwhile, tensions in the Middle East continue to threaten global energy markets.
When uncertainty rises, demand for the dollar often increases.
THE EURO HAS A FRANCE PROBLEM
One of the biggest sources of pressure on the euro is France.
French government bonds have come under heavy selling pressure as investors question how quickly the country can bring its deficit under control.
The French 10-year government bond yield has moved close to 5%, significantly higher than earlier this year.
The spread between French and German 10-year bond yields has also widened.
That spread matters because it reflects the extra return investors demand to hold French debt rather than German government bonds, which are generally treated as the benchmark for eurozone sovereign debt.
As the gap widens, concerns about financial fragmentation within the eurozone grow.
And when investors become more cautious about one of Europe's largest economies, the euro can feel the pressure.
FRANCE'S FISCAL PROBLEM IS BECOMING A CURRENCY PROBLEM
France's fiscal difficulties have been building for years, but higher global interest rates are making them harder for markets to ignore.
Government borrowing is becoming more expensive.
Existing debt must be refinanced at higher rates.
And investors are demanding more compensation for taking on French sovereign debt.
Political uncertainty is adding to the pressure.
France is heading toward a presidential election in 2027, while political divisions at home are making it harder to convince markets that deficit reduction will happen quickly.
That has raised concerns that France could become the focal point of another period of financial stress in the eurozone.
This does not mean Europe is heading for a repeat of the 2010–12 sovereign debt crisis.
But investors are clearly becoming more cautious.
THE FED IS HELPING THE DOLLAR
Federal Reserve policy remains another important part of the story.
Minutes from the September meeting showed that policymakers unanimously supported a quarter-point rate increase, but there was disagreement over what should happen next.
Some officials remained concerned that inflation could stay too high and require further tightening.
Others preferred to wait for more economic data before making another move.
Markets currently expect the Fed to keep rates unchanged at its October meeting, while assigning a much higher probability to another increase in December.
That uncertainty is helping the dollar.
Even without an immediate rate hike, investors are no longer convinced that U.S. monetary policy is heading toward rapid easing.
OIL IS ADDING TO THE DOLLAR'S ADVANTAGE
Oil is another major piece of the puzzle.
Brent crude has moved back above $100 a barrel as attacks on shipping around the Gulf and continuing Middle East tensions raise concerns about energy supplies.
Higher oil prices create a fresh inflation risk.
For the Federal Reserve, that could make it harder to ease monetary policy quickly.
For Europe, the situation may be even more difficult.
The eurozone is heavily dependent on imported energy. Higher oil prices increase the region's import bill and can add to inflation at a time when economic growth is already under pressure.
The United States, by comparison, is a major energy producer.
That difference can give the dollar another relative advantage when energy prices rise.
THE BOND MARKET IS DRIVING THE CURRENCY MARKET
The latest move in currencies cannot be separated from the global bond selloff.
U.S. Treasury yields have risen sharply, while European government borrowing costs have also moved higher.
But the increases have not been equal.
Markets are demanding larger risk premiums from countries with weaker fiscal positions, with France facing particular pressure.
Italy and Greece have also seen their borrowing costs rise relative to Germany.
That divergence is adding to the pressure on the euro.
At the heart of the move is a simple question:
Where is the safest place to hold money while global borrowing costs are rising?
For now, many investors are still choosing the U.S. dollar.
A STRONG DOLLAR IS NOT ENTIRELY GOOD NEWS FOR AMERICA
A stronger dollar has some clear benefits for the United States.
Imported goods become cheaper in dollar terms, while imported energy costs can also fall. That can help ease inflation.
But there is a trade-off.
A stronger dollar makes American goods more expensive for overseas buyers, potentially hurting exporters.
U.S. multinational companies can also feel the impact when foreign revenue is converted back into dollars.
For technology, industrial and consumer companies with significant international sales, a stronger dollar can therefore become a drag on earnings.
So while dollar strength can help contain imported inflation, it is not an unqualified positive for the U.S. economy.
EUROPE FACES A DIFFICULT COMBINATION
The eurozone is dealing with several pressures at once:
Higher energy prices.
Higher government borrowing costs.
Fiscal concerns in France.
Political uncertainty.
Weaker confidence.
Slower economic momentum.
The European Central Bank faces a difficult balancing act.
Higher inflation could argue for tighter monetary policy.
But weak growth and financial instability could call for caution.
If investors begin to believe the ECB has limited room to respond because of pressure in sovereign bond markets, they could demand an even higher risk premium for eurozone assets.
That could put additional pressure on the euro.
SPAIN AND OTHER EUROPEAN RISKS ARE ADDING TO THE PRESSURE
France is not the only political concern in Europe.
Spain has also entered a period of uncertainty following political developments that raised the possibility of a snap election.
Investors are increasingly watching political developments across Europe for signs that instability could interfere with fiscal policy.
That matters because government bond markets have become less forgiving in an environment of high interest rates.
When borrowing costs are already elevated, political uncertainty can quickly translate into higher bond yields.
And higher borrowing costs can eventually become a currency problem.
WHAT DOES A WEAKER EURO MEAN FOR EUROPEANS?
A weaker euro can benefit European exporters.
European products become cheaper for overseas buyers, potentially supporting manufacturing, tourism and other export-oriented industries.
But there is a downside.
Imported goods become more expensive, including energy and commodities.
That can add to inflation.
If the euro falls while oil prices rise, Europe faces a particularly difficult combination:
More expensive energy + weaker currency = stronger imported inflation.
That could put additional pressure on households and businesses already dealing with high borrowing costs.
EMERGING MARKETS ARE WATCHING THE DOLLAR
The dollar's strength matters well beyond the United States and Europe.
Many emerging economies borrow in dollars or rely heavily on commodities priced in dollars.
When the greenback rises, their local currencies can come under pressure.
That can make dollar-denominated debt more expensive to service and increase the cost of importing oil and other commodities.
For countries such as India, a stronger dollar combined with crude oil above $100 creates a difficult external-balance equation.
The pressure can show up through the currency, inflation and higher import costs.
JAPAN IS FACING ITS OWN CURRENCY PROBLEM
The dollar has also remained strong against the yen.
The dollar was recently around 158.22 yen.
Japanese authorities remain sensitive to excessive yen weakness because it raises the cost of imported energy and other commodities.
Markets are therefore watching closely for signs that Tokyo could intervene to support the currency.
But intervention alone cannot permanently reverse major differences in interest rates.
As long as U.S. yields remain significantly higher, the dollar retains an important advantage.
THE SAFE-HAVEN TRADE IS BACK
The latest currency moves reflect a broader shift toward defensive positioning.
Investors are dealing with several sources of uncertainty at the same time:
Middle East conflict
Oil above $100
Global bond-market volatility
European fiscal concerns
Higher U.S. Treasury yields
Uncertainty over central-bank policy
In that environment, the dollar remains one of the world's most important safe-haven currencies.
That does not necessarily mean investors believe everything is going well in the United States.
It means that, for now, the alternatives appear less attractive.
That distinction matters.
WHY THIS MATTERS
The dollar-euro exchange rate is one of the world's most important financial prices.
It affects trade, energy costs, inflation, corporate earnings, tourism and international investment flows.
The euro's slide toward $1.12 therefore matters well beyond currency traders.
If the dollar continues strengthening while oil remains above $100, Europe could face another round of imported inflation.
If U.S. Treasury yields stay elevated, global borrowing conditions could remain tight.
And if European fiscal concerns worsen, the euro could face additional pressure.
FACT CHECK METER
FACT METER: 98%
STATUS: DEVELOPING
CONFIRMED:
The euro fell near $1.1191 on October 8, close to its lowest level in 17 months, while the U.S. Dollar Index moved near an 18-month high.
CONFIRMED:
The dollar is being supported by elevated U.S. Treasury yields and expectations that the Federal Reserve may need to maintain or increase interest rates because of persistent inflation risks.
CONFIRMED:
French fiscal concerns and rising government bond yields have contributed significantly to the euro's recent weakness.
IMPORTANT DISTINCTION:
The euro's decline does not mean the eurozone is experiencing another sovereign-debt crisis on the scale of 2010–12. Current market stress is significant, but that comparison remains a risk scenario rather than an established fact.
AWX VERDICT:
The dollar is benefiting from both higher U.S. yields and weakness in Europe. Unless European fiscal concerns ease or U.S. yields fall substantially, the euro could remain under pressure.
AWX FOCUS
The most important part of this currency story is that the dollar's strength is increasingly relative.
It is not simply that investors have suddenly become more optimistic about the United States.
They are also becoming more concerned about Europe.
French debt worries, political uncertainty and higher energy costs are putting pressure on the euro just as U.S. Treasury yields are offering investors relatively attractive returns.
That combination is powerful.
It could keep the dollar elevated even if U.S. economic data begins to lose some momentum.
WHAT TO WATCH NEXT
1. EUR/USD
A sustained break below recent lows could open the door to further euro weakness.
2. FRENCH BOND YIELDS
Any further widening against German yields would add to pressure on the euro.
3. U.S. 10-YEAR YIELD
Another move toward or above recent highs could provide additional support for the dollar.
4. FED POLICY
Markets will closely watch inflation and employment data for clues about the possibility of a December rate increase.
5. OIL PRICES
Higher crude prices could simultaneously support the dollar and put additional pressure on the eurozone.
6. ECB POLICY
Investors will watch how the European Central Bank responds to rising financial-fragmentation risks.
7. JAPANESE YEN
Any official intervention around 158–160 yen per dollar could have wider implications for global currency markets.
THE AWX BOTTOM LINE
The dollar is rising as investors look for stability in an increasingly uncertain global market.
U.S. Treasury yields are high.
The Federal Reserve remains focused on inflation.
Oil prices are rising.
And Europe is facing growing fiscal and political uncertainty.
Against that backdrop, the euro has slipped toward a 17-month low.
The immediate challenge for Europe is not simply a weaker currency. It is the combination of a weaker euro, higher oil prices and rising government borrowing costs.
For the United States, a stronger dollar provides some protection against imported inflation, but it could also create pressure for exporters and multinational companies.
The broader message from currency markets is clear:
Global investors are looking for safety — and right now, much of that demand is flowing toward the dollar.
ATTLAS WIRE | AWX WORLD NEWS
Real Stories. Lasting Impact.
Comments
No comments yet.