

The U.S. bond market is flashing a warning that Wall Street cannot afford to ignore.
The benchmark 10-year Treasury yield briefly climbed to 5.364% on October 7, its highest level since 2002, before pulling back after a strong Treasury auction and a decline in oil prices.
Several pressures are converging at the same time: crude oil above $100 a barrel, persistent inflation concerns, rising government borrowing needs and uncertainty over what the Federal Reserve will do next.
The 30-year Treasury yield also climbed to a fresh 24-year high of roughly 5.70%.
The move matters because Treasury yields influence almost every part of the U.S. financial system — from mortgages and corporate borrowing to stock valuations and the government's cost of financing its debt.
The immediate panic has eased.
But the underlying concerns have not.
WHAT HAPPENED?
Treasury investors sold longer-dated government bonds aggressively as concerns over inflation and the U.S. fiscal outlook grew.
Because bond prices and yields move in opposite directions, the selling pushed yields sharply higher.
The 10-year yield reached 5.364% during Wednesday's session, while the 30-year yield climbed as high as 5.704%.
Both levels were the highest seen since 2002.
The move is significant because the 10-year Treasury is one of the world's most closely watched benchmarks for borrowing costs and asset valuations.
When its yield rises, the effects can spread well beyond Washington.
Mortgage rates can move higher. Corporate borrowing becomes more expensive. Stock valuations can come under pressure. Emerging-market currencies may weaken. And the U.S. government's interest costs rise.
WHY ARE TREASURY YIELDS RISING?
There is no single explanation. Several forces are hitting the bond market at once.
Inflation is one of the biggest concerns.
Oil prices have remained elevated as the conflict in the Middle East continues to raise concerns about energy supplies.
Brent crude moved back above $100 a barrel on Wednesday, adding to fears that higher energy costs could keep inflation elevated for longer.
That, in turn, makes investors less confident that interest rates can come down quickly.
Fiscal pressure is another part of the story.
The U.S. government continues to issue large amounts of debt to finance spending and refinance existing obligations.
With deficits remaining high, investors are demanding more compensation to hold longer-term government debt.
Then there is the Federal Reserve.
Fed officials remain divided over how aggressively to respond to inflation and energy-price shocks.
Minutes from the September meeting showed disagreement over the reasons for potentially raising rates and how persistent inflation could become.
THE FED IS CAUGHT IN THE MIDDLE
The jump in bond yields puts the Federal Reserve in an uncomfortable position.
If inflation stays elevated, policymakers may have to keep monetary policy restrictive for longer.
But higher interest rates also increase borrowing costs across the economy.
The September Fed minutes showed that some officials believed a rate increase could be necessary to prevent energy and other price shocks from becoming embedded in inflation.
Others placed greater emphasis on signs of demand-driven inflation.
That disagreement makes the outlook harder for investors to read.
Markets are now watching inflation data, employment figures and energy prices closely for clues about the Fed's next move.
OIL IS MAKING THE BOND MARKET'S PROBLEM WORSE
Oil has become an increasingly important part of the Treasury story.
When crude prices rise sharply, investors worry that inflation could accelerate again.
If inflation remains high, central banks have less room to cut interest rates. That can keep long-term bond yields elevated.
That relationship was visible on Wednesday.
Brent crude moved above $100 while the 10-year Treasury yield climbed to its highest level in 24 years.
Later, as oil prices eased, Treasury yields also pulled back from their highs.
The moves underline how closely investors are currently watching the energy market for clues about inflation.
THE 10-YEAR YIELD IS THE MARKET'S KEY NUMBER
Why does 5.34% matter so much?
The 10-year Treasury yield is far more than another bond-market statistic. It serves as a benchmark for the cost of money across the economy.
Mortgage rates are influenced by long-term Treasury yields. Corporate bonds are priced partly against government debt. Investors use Treasury yields when valuing stocks. Banks also take government bond yields into account when setting lending rates.
In simple terms, higher Treasury yields raise the financial hurdle for households, businesses and investors.
The bigger question is whether the 10-year yield can stay above 5% for an extended period.
If it does, the economic consequences could become increasingly difficult to ignore.
MORTGAGES ARE ALREADY UNDER PRESSURE
American homeowners and prospective buyers are particularly sensitive to the move in Treasury yields.
A sustained rise in long-term yields tends to put upward pressure on mortgage rates, making home purchases more expensive for households already dealing with high property prices.
Higher financing costs can also affect construction.
Developers may become more cautious about starting new projects if borrowing becomes significantly more expensive.
That could slow the housing market even if the broader economy continues to hold up.
WALL STREET FACES A VALUATION TEST
Stocks are also vulnerable when bond yields rise.
When Treasury securities offer higher returns, investors may become less willing to pay extremely high prices for riskier assets.
That is especially relevant for technology and other high-growth companies.
Many of these businesses are valued partly on earnings expected years into the future. Higher interest rates reduce the present value of those future earnings.
That does not automatically point to a stock-market crash.
But it can make investors more selective.
Companies with strong cash flow and current earnings may be better positioned than businesses whose valuations depend heavily on growth far into the future.
THE STRONG TREASURY AUCTION CHANGED THE MOOD
There was also a sign that demand for U.S. government debt remains intact.
The Treasury sold $39 billion of 10-year notes in an auction that attracted strong demand.
The notes priced at a yield of about 5.30%, below the yield prevailing when bids were submitted.
The bid-to-cover ratio came in at 2.77, above the six-auction average of 2.54.
Primary dealers received only about 2.5% of the offering, their smallest share since the aftermath of the global financial crisis.
That suggests investors were willing to step in as yields climbed.
The strong auction helped push Treasury yields back from their session highs.
THIS IS NOT A TREASURY COLLAPSE
That auction result is an important distinction.
A 5.36% 10-year yield does not, by itself, mean investors have lost confidence in U.S. government debt.
If anything, the strong auction showed that buyers remain interested when yields become attractive enough.
The issue is that investors appear to be demanding a higher return for taking on long-duration risk.
That is very different from a disorderly collapse in demand.
For now, the Treasury market looks more like a repricing of risk than a complete breakdown.
THE FISCAL QUESTION IS GETTING LOUDER
One of the deeper concerns is the U.S. government's long-term borrowing position.
The United States faces substantial budget deficits and must continually refinance existing debt.
As yields rise, the cost of servicing that debt rises as well.
That can create a difficult cycle:
Higher deficits → more borrowing → greater Treasury supply → higher yields → larger interest payments → greater fiscal pressure.
Investors are increasingly looking for evidence that Washington can manage that trajectory.
That does not mean the market is expecting an immediate U.S. debt crisis.
But fiscal policy is becoming a more important factor in how Treasury securities are priced.
CORPORATE BORROWING COULD ADD ANOTHER LAYER
Another factor is competition for investor capital.
Reuters reported that SpaceX is considering raising roughly $40 billion through bank loans and investment-grade debt to help finance purchases of Nvidia chips.
Large corporate borrowing could compete with Treasury securities for available investment capital.
If companies begin issuing large amounts of long-term debt while the U.S. government is also bringing substantial volumes of Treasuries to market, investors may demand higher yields across the broader credit market.
That could push borrowing costs even higher.
THE YIELD CURVE IS ALSO SENDING A SIGNAL
Another signal is coming from the shape of the Treasury yield curve.
The spread between the 2-year and 10-year Treasury yields widened to around 52 basis points on Wednesday, reaching approximately 53.7 basis points at one point.
The move reflected a bear steepening of the curve, meaning longer-term yields were rising faster than shorter-term yields.
That can point to growing concerns about inflation, fiscal risks or the long-term supply of government debt.
It is another reason investors are paying close attention to the long end of the Treasury market.
GLOBAL MARKETS ARE FEELING THE EFFECT
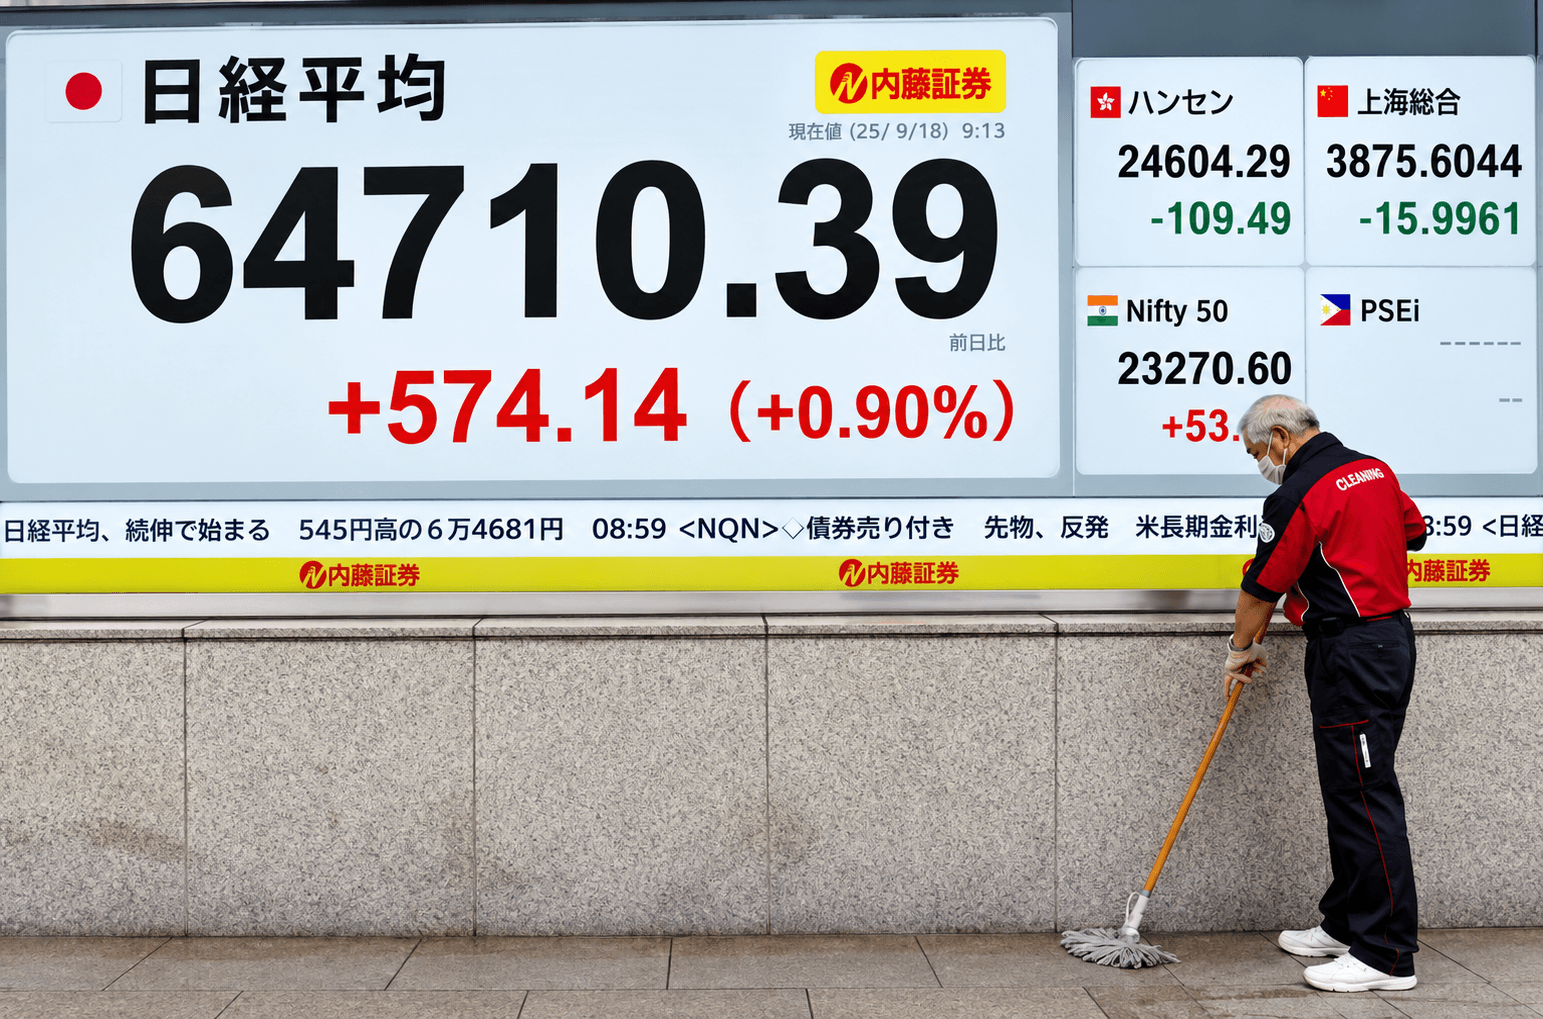
The Treasury selloff is not limited to the United States.
U.S. government bonds play a central role in global financial markets because they are among the world's most widely held and traded assets.
When U.S. yields rise, investors can demand higher returns from other markets as well.
That can put pressure on emerging-market currencies and government bonds, particularly in countries that rely heavily on foreign capital.
India, for example, has already seen pressure on its currency as global bond yields and oil prices have climbed.
WHY THIS MATTERS FOR AMERICAN HOUSEHOLDS
The Treasury market may seem far removed from everyday life, but its effects can eventually reach consumers.
A sustained rise in yields can mean:
Higher mortgage rates.
More expensive car loans.
Higher borrowing costs for businesses.
More expensive government financing.
Pressure on investment portfolios.
Higher financing costs for housing and infrastructure.
In effect, the bond market is repricing the cost of money across the U.S. economy.
WHY THIS MATTERS FOR INFLATION
There is an important contradiction at work.
Higher bond yields can eventually slow the economy and help bring inflation down.
But part of the reason yields are rising now is that investors are worried inflation may remain elevated.
Energy prices are at the center of that concern.
If oil remains above $100, inflation could prove harder to bring down.
If inflation stays sticky, the Fed could keep rates higher.
And if rates stay higher, Treasury yields may remain elevated.
That creates the possibility of tighter financial conditions lasting longer than markets had expected.
FACT CHECK METER
FACT METER: 99%
STATUS: DEVELOPING
CONFIRMED:
The U.S. 10-year Treasury yield reached 5.364% on October 7, 2026, its highest level since 2002.
CONFIRMED:
The 30-year Treasury yield also reached a 24-year high of approximately 5.70%.
CONFIRMED:
A $39 billion 10-year Treasury auction attracted strong demand and helped yields retreat from their session highs.
CONFIRMED:
Higher oil prices, inflation concerns, fiscal deficits and uncertainty over Federal Reserve policy are contributing to pressure on longer-term Treasury yields.
IMPORTANT DISTINCTION:
A 5.34% 10-year yield does not by itself signal a U.S. debt crisis. Strong Treasury auction demand indicates that investors are still willing to buy government debt when yields are sufficiently attractive.
AWX VERDICT:
The bond market is experiencing serious volatility, but the latest move is better understood as a sharp repricing of long-term borrowing risk than as a collapse in demand for U.S. Treasuries.
AWX FOCUS
The 5.34% figure is important.
But what happens next may matter even more.
If the 10-year yield settles around current levels, markets may gradually adjust.
If it moves substantially higher, the consequences could spread much further across the economy and financial markets.
The key risks are now clear:
Oil above $100.
Sticky inflation.
Large fiscal deficits.
Heavy Treasury issuance.
Uncertain Fed policy.
Taken together, those forces could keep pressure on the long end of the bond market.
WHAT TO WATCH NEXT
1. THE 10-YEAR YIELD
Whether it holds above 5% or moves toward new multi-decade highs.
2. THE 30-YEAR YIELD
Long-term borrowing costs remain one of the clearest indicators of fiscal and inflation concerns.
3. OIL PRICES
Another sustained move above $100 could intensify inflation fears.
4. TREASURY AUCTIONS
Strong demand would reassure investors that higher yields are attracting buyers.
5. FED POLICY
Any change in expectations for future rate moves could send yields sharply higher or lower.
6. INFLATION DATA
Investors need clearer evidence that price pressures are cooling.
7. STOCK VALUATIONS
Technology and other high-growth shares could remain particularly sensitive to rising yields.
THE AWX BOTTOM LINE
The U.S. bond market has crossed an important psychological threshold.
The 10-year Treasury yield briefly reached 5.364%, its highest level since 2002.
That is a significant move.
But the strong Treasury auction that followed provided an important counter-signal: investors are still willing to buy U.S. government debt when the yield is attractive enough.
The bigger question now is whether 5.34% becomes a ceiling — or a new floor.
If oil prices fall, inflation cools and demand for Treasuries remains strong, yields could move lower.
If energy prices stay elevated and fiscal concerns deepen, the bond market could face another round of selling.
Wall Street may be watching stocks. But right now, one of the clearest signals about where markets are heading is coming from the bond market.
ATTLAS WIRE | AWX WORLD NEWS
Real Stories. Lasting Impact.
Comments
No comments yet.